

Quick Answer: Truck insurance in Gilbert, AZ protects your vehicle against accidents, theft, and liability claims. Personal pickup owners need standard auto coverage meeting Arizona’s minimum requirements, while commercial truck operators require specialized policies including liability, physical damage, and often cargo coverage. Working with an independent broker helps Gilbert truck owners compare rates from multiple carriers to find the right protection.
Whether you haul equipment for your Gilbert-based business or drive a personal pickup around Maricopa County, understanding truck insurance basics helps you make smart coverage decisions. Arizona’s diverse terrain—from desert highways to mountain passes—creates unique risks that your policy should address.
This guide explains the coverage types Gilbert truck owners need, how personal and commercial policies differ, and what factors influence your rates. You’ll learn how to evaluate policies and find coverage that fits your specific situation.
Understanding Truck Insurance Basics in Arizona
Truck insurance works similarly to standard car insurance, but policies vary significantly based on how you use your vehicle. Arizona law requires all motor vehicles to carry minimum liability coverage, but trucks often need additional protection due to their size, value, and common uses.
The Arizona Department of Transportation registers thousands of commercial trucks operating throughout Maricopa County. Gilbert’s growing business community includes contractors, delivery services, and freight operators who all depend on properly insured trucks to stay operational.
For personal truck owners, your policy structure mirrors typical auto insurance. For commercial operators, you’ll need specialized coverage that addresses business-specific risks like cargo damage, employee accidents, and higher liability limits that protect your company assets.
Personal Truck Insurance Coverage in Gilbert
Personal pickup trucks represent one of Arizona’s most popular vehicle types. If you use your truck primarily for commuting, errands, and occasional hauling, a standard personal auto policy typically provides adequate coverage.
Required Arizona Coverage
Arizona mandates minimum liability coverage for all registered vehicles. These minimums apply to personal trucks driven in Gilbert:
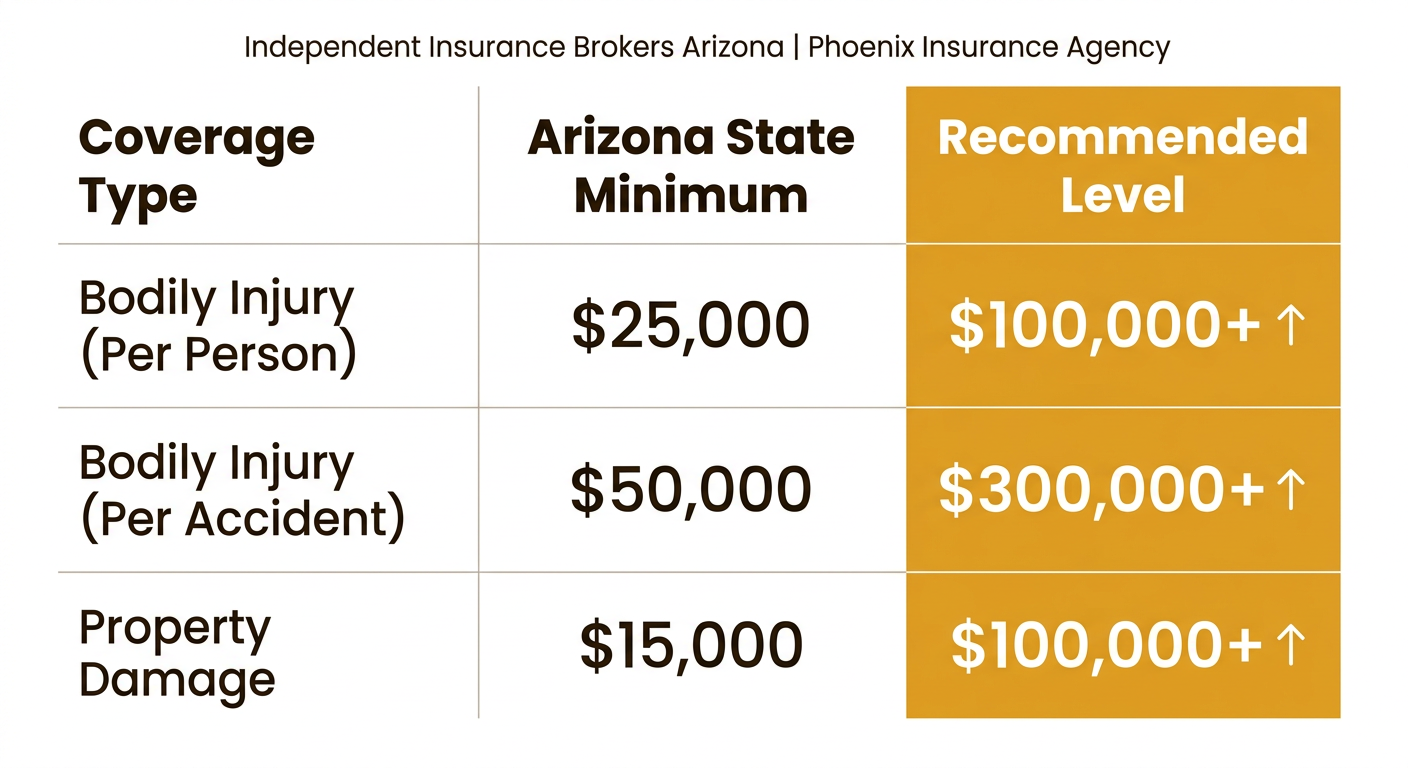
Coverage TypeArizona MinimumRecommended LevelBodily Injury (per person)$25,000$100,000+Bodily Injury (per accident)$50,000$300,000+Property Damage$15,000$50,000+
Most insurance professionals recommend coverage well above state minimums. Trucks involved in accidents often cause more damage than smaller vehicles, making higher liability limits a wise investment for Gilbert truck owners.
Optional Coverage Worth Considering
Beyond liability, several additional coverage types protect your truck investment. Collision coverage pays for damage when your truck hits another vehicle or object. Comprehensive coverage handles non-collision events like theft, vandalism, hail, and fire damage.
Gilbert’s summer monsoon season brings intense storms that can damage vehicles through flooding, wind-blown debris, and hail. Understanding monsoon-related coverage helps ensure your policy addresses these regional weather risks.
Uninsured motorist coverage becomes particularly important in Arizona. According to the Insurance Information Institute, Arizona consistently ranks among states with higher uninsured driver rates, making this protection valuable for Gilbert truck owners.
Commercial Truck Insurance Requirements
If you use your truck for business purposes—hauling materials, making deliveries, or transporting goods for hire—personal auto policies typically won’t cover claims. Commercial truck insurance addresses the higher risks and liability exposure that business use creates.
The Federal Motor Carrier Safety Administration sets insurance requirements for interstate commercial trucking, while Arizona regulates intrastate commercial vehicles. Gilbert contractors and delivery operators must understand which regulations apply to their specific operations.
Primary Commercial Coverage Types
Commercial truck policies combine several coverage components. Understanding what the average cost of commercial truck insurance includes helps you budget accurately and compare quotes effectively.
Primary Liability Insurance covers bodily injury and property damage you cause to others. Federal requirements range from $300,000 to $5 million depending on cargo type, with higher limits required for hazardous materials haulers.
Physical Damage Coverage protects your truck itself. This includes collision coverage for accident damage and comprehensive coverage for theft, fire, and weather events. Values depend on your truck’s age, condition, and market worth.
Cargo Insurance protects the goods you transport. Coverage limits and requirements vary based on cargo type, with specialized policies available for refrigerated goods, automotive parts, household items, and other categories.
Need Help Finding the Right Truck Coverage?
Independent Insurance Brokers Arizona compares truck insurance options from over 40 carriers to find competitive rates for Gilbert truck owners. Request your free quote and let us shop the market for you.
Additional Commercial Protections
Beyond primary coverages, commercial truck operators often need supplemental policies. Workers compensation insurance becomes mandatory when you hire drivers or helpers, covering medical expenses and lost wages if employees are injured on the job.
General liability insurance protects against non-vehicle business claims. If a customer injures themselves at your Gilbert location or you damage property while loading cargo, this coverage responds where auto policies don’t.
Many Gilbert trucking operations benefit from umbrella insurance coverage, which provides additional liability protection above your primary policy limits. Given the serious injuries truck accidents can cause, this extra layer often proves essential for business protection.
Factors Affecting Truck Insurance Rates in Gilbert
Several variables influence what you’ll pay for truck insurance in Gilbert. Understanding what factors affect auto insurance rates helps you identify ways to potentially lower your premiums while maintaining adequate coverage.
Vehicle-Specific Factors
Your truck’s characteristics significantly impact pricing. Newer, more valuable trucks cost more to insure because replacement or repair expenses run higher. Heavy-duty trucks carrying larger payloads typically cost more than light-duty pickups due to increased damage potential in accidents.
Safety features and anti-theft devices can reduce premiums. Many insurers offer discounts for trucks equipped with backup cameras, electronic stability control, and recovery systems.
Driver and Usage Factors
Your driving record remains the strongest predictor of insurance costs. Accidents, tickets, and claims within the past three to five years raise rates substantially. Maintaining a clean record offers the most effective way to keep truck insurance affordable.
How you use your truck matters too. Higher annual mileage increases exposure to accidents, while long-haul routes generally cost more to insure than local delivery. The radius you operate within—whether limited to Gilbert or extending throughout Arizona—affects commercial policy pricing.
Your credit history influences insurance rates in Arizona. Insurers use credit-based insurance scores as one factor in determining premiums, making good credit maintenance a worthwhile strategy for lowering costs.
Personal vs. Commercial: Determining Which You Need
The line between personal and commercial truck insurance isn’t always obvious. Making the wrong choice can leave you without coverage when you need it most.
Personal policies typically exclude business use beyond basic commuting. If your employer requires you to use your personal truck for work tasks, you may need a commercial policy or an endorsement adding business coverage to your personal policy.
Understanding whether sole proprietors need commercial auto insurance helps Gilbert business owners make informed decisions. Generally, if your truck displays business logos, hauls equipment or materials for paying customers, or serves as a primary tool of your trade, commercial coverage applies.
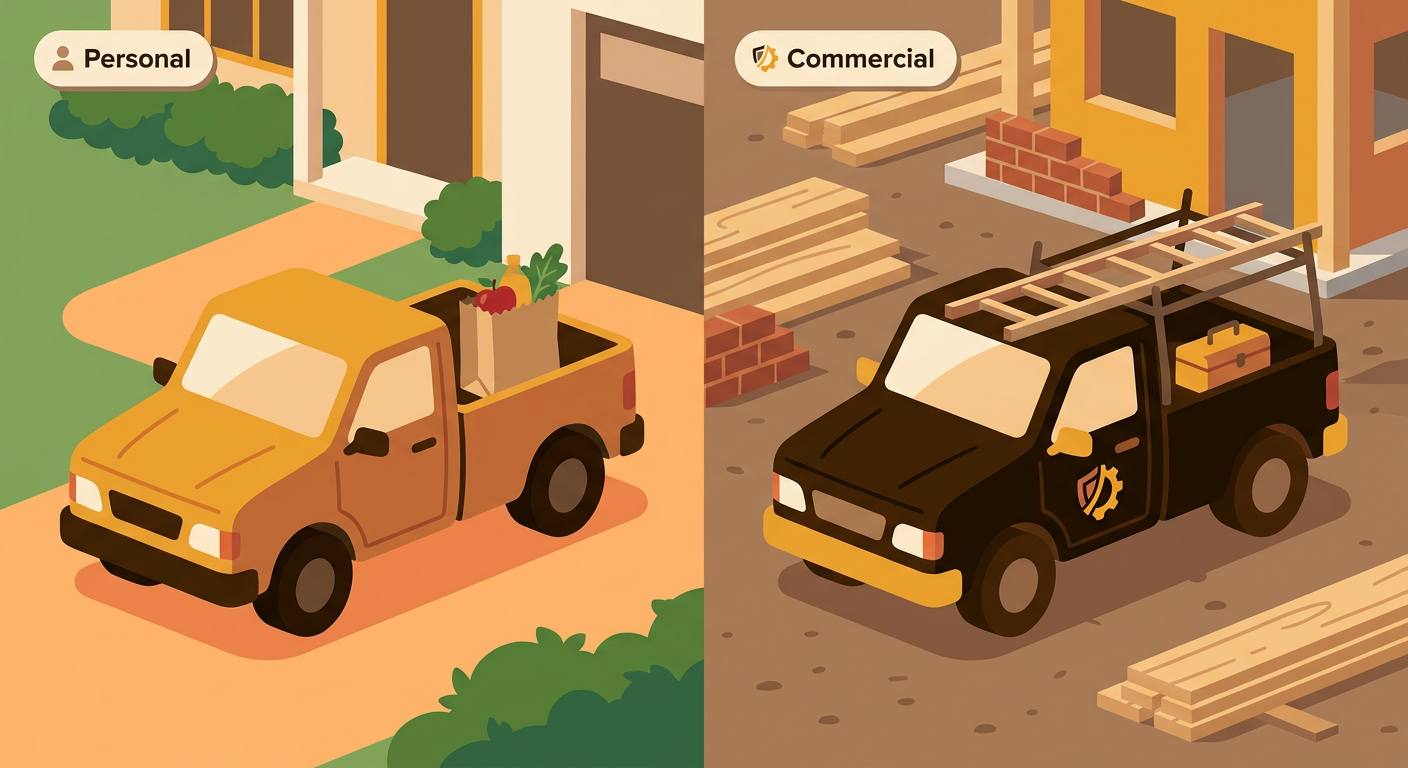
The differences between commercial, business, and personal auto insurance can be confusing. Speaking with an independent broker helps clarify which policy structure fits your situation and ensures no coverage gaps exist.
Finding the Right Truck Insurance in Gilbert
Gilbert truck owners have multiple options for purchasing coverage. Understanding the value of working with an insurance broker versus going directly to a single carrier helps you make the best choice for your needs.
Independent brokers like Independent Insurance Brokers Arizona work with multiple insurance carriers rather than representing just one company. This allows comparison shopping with a single application, often revealing rate differences of hundreds of dollars annually for the same coverage levels.
For commercial truck insurance especially, carrier specialization matters. Some insurers focus on long-haul trucking while others excel with local delivery fleets or construction contractors. An experienced broker knows which carriers best serve different Gilbert business types.
Questions to Ask When Shopping
When evaluating truck insurance options, ask specific questions about coverage details. What deductible options are available, and how do they affect premiums? Are there discounts for safety equipment, good driving records, or paying annually?
For commercial policies, understand how the carrier handles claims. Fast claims processing keeps your trucks on the road and your business running. Ask about the insurer’s financial strength rating and claims satisfaction scores before committing.
Understanding how much insurance you actually need prevents both overpaying for unnecessary coverage and being underinsured when claims occur. Your broker should help you assess your specific risk exposure and recommend appropriate limits.
Managing Your Truck Insurance Over Time
Insurance needs change as your situation evolves. Regular policy reviews ensure your coverage keeps pace with your circumstances.
If you purchase a new truck, upgrade an existing vehicle, or change how you use your truck, notify your insurer promptly. Policy modifications mid-term typically incur small fees but ensure continuous coverage for your actual situation.
When considering switching carriers, learn how to switch car insurance without a coverage lapse. Continuous coverage history affects your rates, so proper transition timing matters.
Gilbert business owners expanding their fleets should discuss fleet insurance options with their broker. Policies covering multiple trucks often offer volume discounts and simplified administration compared to individual policies on each vehicle.
Gilbert’s Unique Insurance Considerations
Gilbert’s location within the Phoenix metropolitan area creates specific insurance considerations. The town’s rapid growth has increased traffic density, affecting accident frequency and claim costs throughout Maricopa County.
Summer conditions in Chandler and Gilbert stress vehicles significantly. Extreme heat can cause tire blowouts and mechanical failures, while monsoon storms bring flash flooding that can strand trucks in low-lying areas. Comprehensive coverage protects against these weather-related losses.
Gilbert’s mix of residential neighborhoods, commercial districts, and agricultural areas means truck drivers navigate varied environments daily. Your policy should account for the specific roads and conditions you encounter regularly.
Get Your Gilbert Truck Insurance Quote Today
Independent Insurance Brokers Arizona helps truck owners throughout Gilbert, Mesa, Chandler, and the Phoenix metro area find competitive coverage from 40+ insurance carriers. Call us at (480) 893-2260 or contact our team to discuss your truck insurance needs.
Frequently Asked Questions
Do I need commercial truck insurance if I only use my truck for side jobs in Gilbert?
If you receive payment for services involving your truck—such as hauling, delivery, or moving assistance—most personal auto policies exclude these activities. Even occasional paid work typically requires commercial coverage or a business use endorsement. Check with your broker to confirm your specific policy terms and add appropriate coverage before accepting paid jobs.
How much does truck insurance cost in Gilbert, Arizona?
Truck insurance costs vary widely based on your vehicle type, driving record, coverage levels, and usage. Personal pickup insurance rates depend on many of the same factors as standard auto insurance. Commercial truck policies cost more due to higher liability requirements and specialized coverages. An independent broker can provide accurate quotes for your specific situation by comparing multiple carriers.
What happens if I have an accident while using my personal truck for business?
If you’re using your truck for business purposes and only have personal auto insurance, your claim may be denied. Insurers investigate how vehicles were being used at the time of accidents. Using your truck commercially without proper coverage could leave you personally liable for damages, injuries, and legal costs.
Does Gilbert have any special truck insurance requirements?
Gilbert follows Arizona state insurance requirements for personal vehicles. Commercial trucks operating within town limits must meet state and federal regulations based on vehicle weight, cargo type, and operating radius. Local permits for certain commercial activities may specify additional insurance requirements.
Can I get truck insurance in Gilbert with a less-than-perfect driving record?
Yes, though your options may be limited and rates higher than for drivers with clean records. Independent brokers access multiple carriers, including those specializing in higher-risk drivers. Working with a broker helps identify carriers most likely to offer coverage at competitive rates despite driving history issues.